A chattel mortgage is a type of business car loan used by ABN holders, sole traders and companies in Australia to finance a vehicle or other business asset. You own the asset from day one, while the lender registers a “mortgage” (a security interest) over it until the loan is paid off — hence the name. The Lending Link is a broker-matching platform, not a lender: we match ABN holders with accredited brokers to compare finance options.
Who Is a Chattel Mortgage For?
This finance option is built for businesses and ABN holders, not private buyers. It typically suits:
- Sole traders and self-employed contractors buying a work vehicle
- Companies and partnerships financing cars, utes or vans for business use
- Businesses registered for GST looking to claim the GST credit upfront (capped by the ATO’s GST car limit)
- Anyone who wants to own the asset outright from the start, rather than lease it
If you’re buying purely for personal use, a personal car loan is usually the better fit — see our guide to chattel mortgage vs personal loan for how to decide.
How Does It Work?
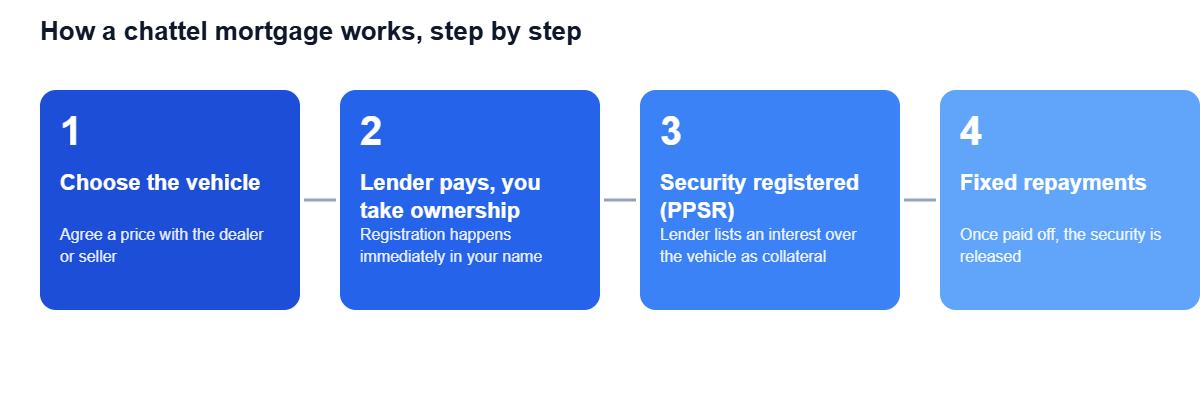
- You choose the vehicle and agree a purchase price with the dealer or seller.
- The lender pays for the vehicle on your behalf and you take ownership and registration immediately.
- The lender registers a security interest (via the Personal Property Securities Register) over the vehicle as collateral for the loan.
- You make fixed repayments over an agreed term, typically 1 to 7 years.
- Once the loan is repaid, the security is released and the vehicle is fully and clearly yours.
Because you own the asset from the outset, this structure is often chosen over a lease by businesses that want the vehicle on their balance sheet as an asset rather than an ongoing expense.
How It Compares to Other Finance Options
| Option | Who owns it | Best for |
|---|---|---|
| Chattel mortgage | You, from day one | ABN holders who want to own the asset and claim GST/tax benefits |
| Personal car loan | You, from day one | Private buyers with no business use |
| Novated lease | Leasing company | Employees financing a car through salary packaging |
| Hire purchase | Lender until final payment | Businesses that prefer to pay off ownership progressively |
For a closer look at two of these side by side, see chattel mortgage vs personal loan, or read our broader business car loan guide for ABN holders and sole traders.
Pros and Cons of a Chattel Mortgage
Potential advantages:
- You own the vehicle immediately, with no restrictions on how it’s used within reason
- Eligible businesses may claim the GST on the purchase price upfront
- Interest and depreciation on the business-use portion may be tax-deductible
- Fixed repayments make budgeting straightforward
- No mileage limits or lease-end conditions, unlike some lease products
Things to weigh up:
- You carry the depreciation risk, since the asset is yours
- Early payout may attract fees depending on the lender
- Approval depends on business financials and ABN history, which can be a hurdle for very new businesses
Tax Treatment of a Chattel Mortgage
One of the main reasons ABN holders choose this finance option is the potential tax treatment: GST on the purchase price may be claimable upfront if you’re registered for GST, and interest plus depreciation on the business-use portion of the vehicle may be tax-deductible. Read more in our chattel mortgage tax benefits guide.
This is general information only, not tax advice. Every business’s situation is different — confirm with your accountant before you commit.
How to Apply for a Chattel Mortgage
Most lenders will ask for your ABN details, recent business bank statements, photo ID, and details of the vehicle you want to finance. Rather than approaching one lender at a time, The Lending Link matches you with accredited brokers who compare finance options across their panel on your behalf — free to use, with no obligation.
Get matched with a chattel mortgage broker →
Frequently Asked Questions
What does “chattel” mean?
“Chattel” simply refers to a movable item of property — in this case, the vehicle or asset being financed. The “mortgage” part refers to the lender’s security interest over that asset.
Is a chattel mortgage only for cars?
No. While it’s most commonly used for business vehicles, a chattel mortgage can also finance other business assets like machinery, equipment and trucks.
Do I need an ABN to get a chattel mortgage?
Yes. A chattel mortgage is a business finance product, so you’ll need an active ABN and the vehicle needs to be predominantly used for business purposes.
Can a new business get a chattel mortgage?
It’s possible, though most lenders prefer at least 12 months of ABN registration and trading history. Some lenders do consider newer businesses on a case-by-case basis.
What happens at the end of the loan?
Once you’ve made all your repayments, the lender releases its security interest and the vehicle is fully and clearly yours, with no further payments or conditions.
Is The Lending Link a lender?
No. The Lending Link is a broker-matching platform. We connect you with accredited brokers who arrange chattel mortgage finance on your behalf — we don’t lend the money ourselves.